By: Nkosiyabusa Nsibande
Businesses in Eswatini face growing pressure to strengthen their financial resilience against climate-related events, cyber threats and other emerging risks, with Ensure Insurance Brokers Chief Executive Officer Lovemore Vilane warning that insurance protection must be supported by deliberate risk management if companies are to limit losses and sustain operations during disruptions.
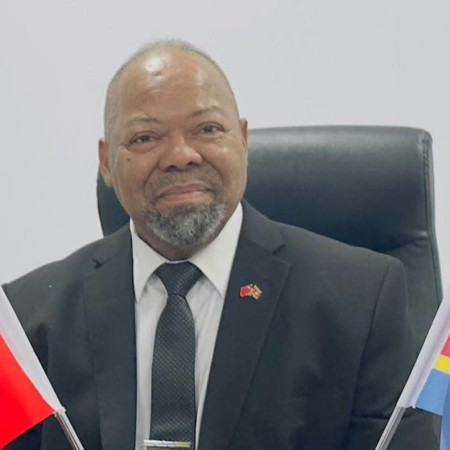
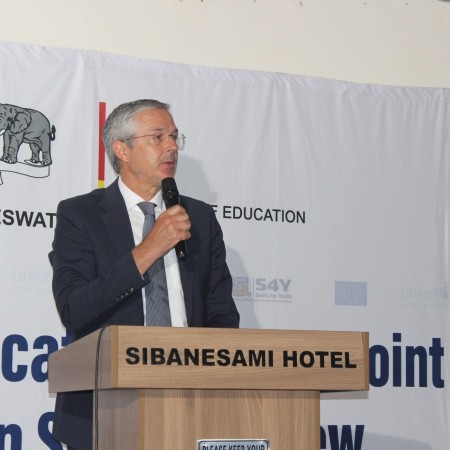
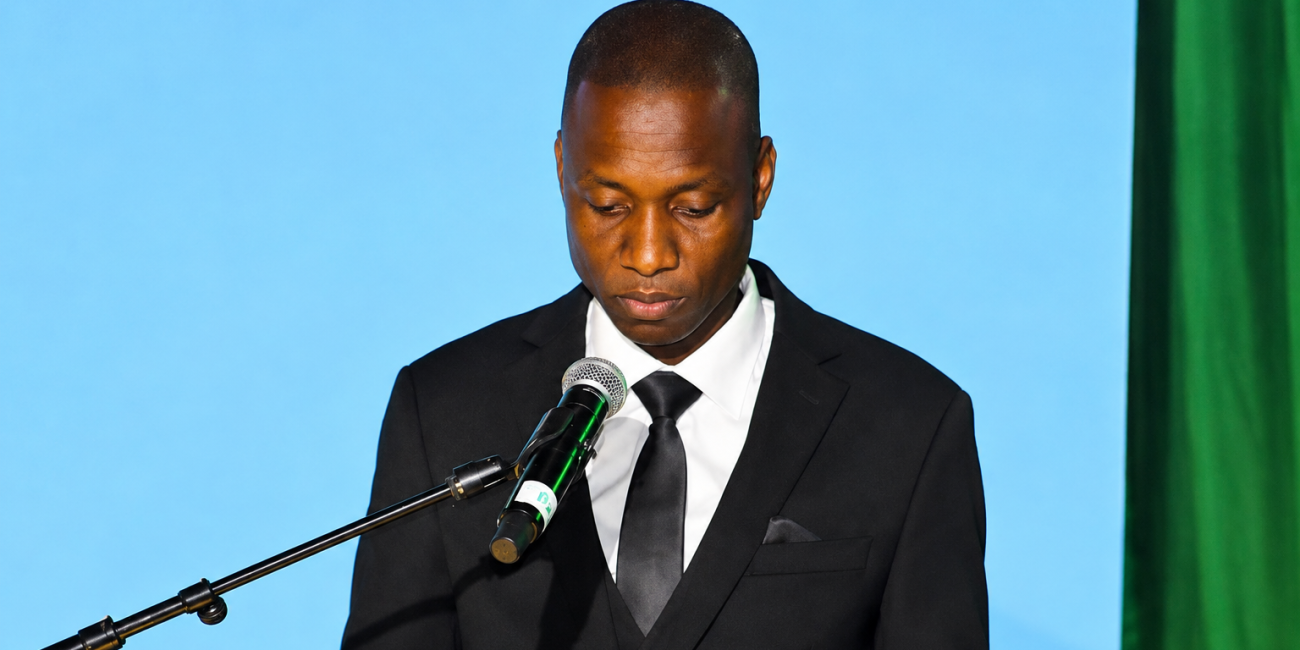
Speaking at the Insurance & Risk Management Leadership Dinner held at Happy Valley Hotel on Friday, 23 October 2026, Vilane argued that insurance remains a critical financial safeguard but cannot substitute for preventive measures, sound governance, and contingency planning. The second edition of the gathering, held under the theme Beyond What’s Next – Shaping the Future of Insurance & Risk, brought together business leaders from Eswatini, South Africa, and Mozambique to discuss the changing risk environment and its implications for organizations.
“Insurance remains essential. It protects businesses financially, supports recovery, and enables economic activity,” Vilane said.
The financial implications extend beyond the immediate cost of repairing damaged property or replacing lost equipment. For businesses, an uninsured or inadequately insured loss can deplete working capital, interrupt revenue generation, increase borrowing requirements, and delay investment plans. Companies that cannot resume operations quickly may also struggle to meet contractual obligations, service debt, and retain customers, making risk preparedness an important consideration in financial planning rather than simply an insurance administration function.
Climate exposure is particularly relevant to Eswatini’s business environment, where weather-related disruptions can affect agricultural production, physical assets, and supply chains. The Central Bank of Eswatini’s Financial Stability Review for June 2024 identified climate change as an escalating risk to the insurance industry, highlighting the implications of extreme weather for claims, underwriting, and the sustainability of insurance operations. The review also pointed to the importance of incorporating climate-related risks into insurers’ risk management frameworks.
This creates a financial challenge for both policyholders and insurers. Businesses must assess whether their existing policies adequately reflect the value of their assets and their exposure to operational disruption, while insurers must evaluate the risks they accept, price coverage appropriately, and maintain the capacity to meet claims. Where risk assessments are weak, or insurance arrangements do not align with actual exposures, companies may discover significant protection gaps only after a loss has occurred.
Vilane identified climate-related events, along with cyber threats, artificial intelligence, geopolitical tensions, and economic uncertainty, as interconnected risks that can disrupt businesses and entire industries. Their interaction is important because a single disruption can trigger several financial consequences simultaneously, from production stoppages and lost sales to additional security costs, contractual penalties, and pressure on cash flow.
For example, a severe weather event affecting a company’s premises or supplier network may interrupt production while increasing the cost of sourcing replacement inputs. A cyber incident can similarly disrupt transactions, compromise sensitive information, and require expensive recovery measures. When businesses lack adequate contingency arrangements or appropriate insurance coverage, these costs can place additional pressure on liquidity and threaten their ability to continue operating. Against this backdrop, Vilane called on corporate leaders to embed risk management into their strategic and financial decisions, rather than treating it as an exercise undertaken when policies are renewed or claims arise. “Risk management must become part of how we lead, plan, invest, and make decisions,” he said.
For business owners and financial managers, this means assessing potential losses before committing capital, identifying critical operational dependencies, and establishing realistic recovery plans. It also requires regular reviews of insurance limits, exclusions, deductibles, and policy conditions to determine whether the protection purchased corresponds with the company’s current assets, liabilities, and operating model. Such assessments are particularly important for small and medium-sized enterprises, which may have fewer financial reserves to absorb unexpected losses than larger companies.
The discussion also raises questions about the evolving commercial role of insurance brokers. Traditionally, brokers have helped clients arrange cover, compare products, negotiate premiums, and manage claims. Vilane argued that the changing risk environment requires a more advisory approach in which brokers help businesses understand their exposures, identify shortcomings in existing protection, and make informed decisions about managing risk. “The future of insurance broking will depend not only on the products we can access but also on the quality of the advice, insight, and value we bring to the businesses we serve,” he said.
A stronger advisory relationship could help businesses make more informed decisions about the balance between transferring risk through insurance and managing it internally through prevention, security controls, and business continuity measures. For insurers and brokers, it also places greater emphasis on understanding clients’ operations and ensuring that coverage recommendations reflect their actual financial exposure rather than relying solely on standardized products.
Vilane said stronger partnerships between businesses, insurers, brokers, and risk professionals would be necessary to navigate the changing environment. He added that Ensure is intended to contribute to a stronger risk management culture in Eswatini and Southern Africa by creating opportunities for practical discussions on business resilience.
“Distinguished guests, we cannot predict every disruption or eliminate every risk. But we can become better prepared, make more informed decisions, and build stronger partnerships between businesses, insurers, brokers, and risk professionals,” he said.
The message carries broader implications for corporate governance and financial stability. Effective risk management can help protect productive assets, preserve cash flow, and reduce the likelihood that an operational shock will develop into a wider financial crisis. For businesses seeking to expand, attract investment or secure financing, the ability to demonstrate that material risks have been identified and addressed can also strengthen confidence in their operational and financial management.
Ultimately, the challenge for businesses is to move beyond viewing insurance as a transaction designed to compensate for losses after they occur. As climate exposure, digital threats, and economic uncertainty reshape the operating environment, the financial value of insurance will increasingly depend on how effectively it is combined with prevention, preparedness, and sound decision-making. For Eswatini’s businesses, resilience will require not only appropriate insurance cover but also the financial discipline and organizational capacity to anticipate disruption and recover from it.